Anchored to prices past: managerial beliefs about stock value

20 Oct 2026
11:15 -12:30
Times shown in local time
Open to: All

Room W4.03 (Cambridge Judge Business School)
Trumpington St
Cambridge
CB2 1AG
United Kingdom
Join our Finance seminar
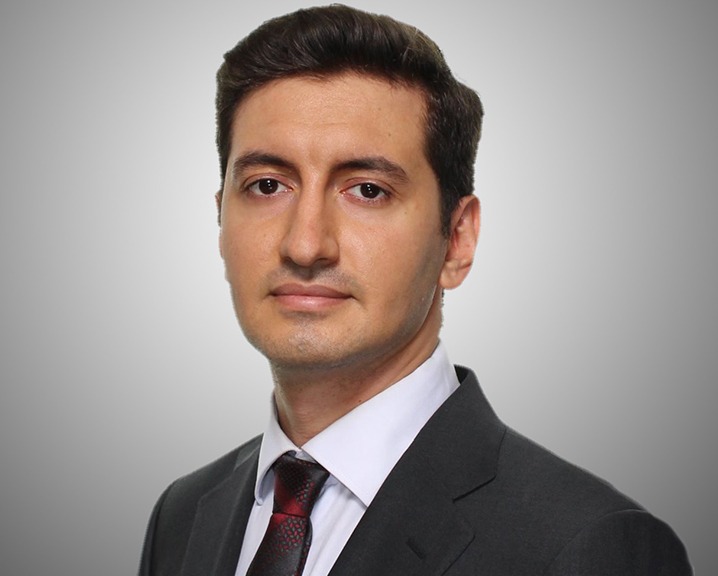
Speaker: Dr Amir Salarkia, Tilburg University
About the seminar topic
Using novel data on explicit undervaluation claims in earnings calls, we study how managers form beliefs about their firms’ stock value. Appearing in only 4.7% of calls, these claims seem to capture genuine managerial beliefs: they generate strong positive price reactions followed by higher earnings and operating cash flows, predict opportunistic repurchases, and are more common when managers have greater long-term equity exposure. Yet these beliefs are anchored to salient past prices: drawdowns from prior peaks predict claims beyond recent returns. Consistent with persistent anchoring, technology firms that experienced extreme dot-com valuations remain more likely than peers listed after the dotcom bubble to claim undervaluation and repurchase shares opportunistically, with both effects weakening as dotcom-era managers leave. Our findings suggest that financial-market bubbles can leave a lasting imprint on managerial beliefs, thereby shaping corporate financial policy long after bubble prices recede.
Speaker bio
Amir joined as Assistant Professor of Finance at Tilburg University and received his PhD in Finance from the London School of Economics in 2023. His research focuses on asset pricing and beliefs in financial markets, with particular interest in how investors and managers form valuation beliefs and how those beliefs affect asset prices and corporate decisions. He also works on mutual funds, portfolio choice and capital flows.
Register
No registration required. If you have any questions about this seminar, please email Bet Brooke.